Trending Now
- “Due to the Union Govt’s failure to properly plan for electricity shortages, Rajasthan is purchasing electricity at Rs.46 per unit.” – Explains Minister Nirmal Kumar on power procurement
- “Despite repeated warnings about the deteriorating law and order situation, the government remains indifferent. It must stop playing with people’s safety.” – DMK MP Kanimozhi
- Microsoft co-founder Bill Gates warns that AI and robotics could pose major challenges to employment opportunities over the next 20 years.
- Reports say Superstar Rajinikanth starrer ‘Jailer 2’ has crossed Rs.700 crore in worldwide box-office collections.


Cooperative banks’ depositors to be biggest beneficiaries of DICGC Bill, 2021

 July 28, 2021
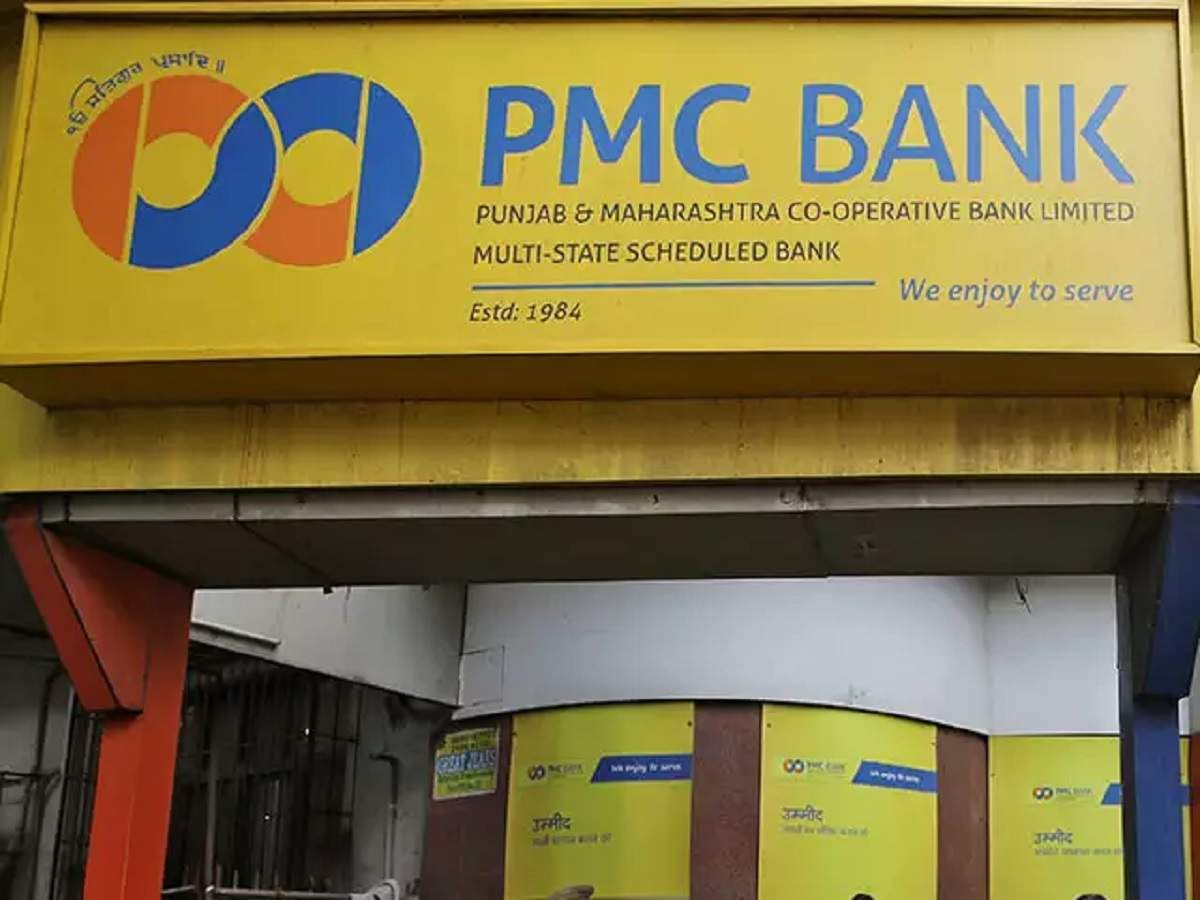

The government’s decision to allow fund access to depositors of banks under a moratorium within 90 days is expected to benefit the cooperative banking sector the most as this segment has seen the maximum moratoriums and liquidation in the last decade.
The poor governance, lack of technology and professional management, political interference, and risky assets or loan mix have seen the cooperative banking space shrinking over the last decade.
The Reserve Bank of India (RBI) has also been quick in taking regulatory action against cooperative banks by putting them under a moratorium and also initiating the liquidation exercise if the assets (loans ) are not sufficient to cover the liabilities.
The cabinet’s approval to the Deposit Insurance and Credit Guarantee Corporation Bill, 2021, allows the depositors of banks under the moratorium access to their money in savings, current and fixed deposit accounts within 90 days.
It is not known whether the entire insured money would be given out at one go or a part of the funds would be released.
Currently, the DICGC insures the depositors up to Rs 5 lakh per customer per bank both for principal and interest.
The premium of Rs 12 paise per Rs 100 deposit is paid by the banks as a premium to DICGC. The corporation covers all banks, including the cooperative banking sector.
“The commercial public and private banks, which controls the bulk of the deposits in the banking sector would end up subsiding the cooperative banking sector,” says a banking official.
There are not many failures in the public and private banking space. IDBI Bank was bailed out by the Life Insurance Corporation of India. Yes Bank was bailed out by a consortium of banks led by the State Bank of India. Similarly, the RBI had found a suitor (DBS Bank) for the old private sector Laxmi Vilas Bank. There has been no liquidation of public or private banks in the last two decades.
In fact, the cooperative banks are the ones facing the RBI’s moratorium quite often and also liquidation in some cases.
“DICGC’s cash flows would also get impacted as they have to keep enough liquid funds to meet the liabilities,” adds the banker.
The cooperative banks’ universe includes all centre, state, and primary cooperative banks, including urban cooperative banks.
However, the primary cooperative societies are not insured by the DICGC.
Currently, the process of getting the insured money from DICGC is quite long. At times, it takes more than three-five years. The moratorium period also gets extended, and only minimum withdrawals are allowed on a monthly basis.